What I built
I built the registered-data pipeline: point-in-time rate gaps, loan-month survival models, local event studies, evidence-tiering, and a public synthetic reproduction path.
Research question and relevance
Question: How does the gap between homeowners' existing mortgage rates and current market mortgage rates affect mortgage exits, housing-market activity, local prices, and new construction?
Mortgage lock-in may remove the same owner from both sides of the market: fewer existing homes may be listed, while repeat-buyer demand may also fall. The project therefore treats lock-in as a measurable state, not an effect, and does not assume the sign of the price response.
Vocabulary boundary: Freddie Mac Zero Balance Code 01 identifies a voluntary payoff or maturity. It does not distinguish a refinance from a sale-related payoff and is not a measure of moving. The loan-level outcome is always described as prepayment or mortgage exit.
Data and publication boundary
The registered analysis uses a 5% loan sample from Freddie Mac cohorts originating from 2013Q1 through 2022Q4, together with PMMS rates, FHFA house-price indexes, HMDA aggregations, Census building permits, BLS labor-market data, and documented geographic crosswalks.
| Material | Public release treatment |
|---|---|
| Source, tests, configuration, documentation | Published on GitHub and mirrored in the Dataset. |
| Synthetic fixtures | Published with explicit SYNTHETIC labeling. |
| Registered Freddie Mac loan records | Never redistributed. |
| Loan-granular derivatives and local caches | Excluded from every public package. |
| Aggregate reports and coefficients | Published with evidence tiers, population statements, and source attribution. |
Capabilities demonstrated
- Construct eight point-in-time lock-in measures without forward-looking rate alignment.
- Build mortgage-exit and competing-risk outcomes with explicit left truncation and censoring.
- Estimate survival summaries and discrete-time hazards at the loan-month level.
- Freeze pre-shock local coupon exposure and estimate state and metropolitan event studies.
- Automatically demote results when pre-trends or placebos fail.
- Keep model-dependent policy scenarios in a separate
simulationtier and never call them forecasts.
Every result artifact is labeled descriptive, hazard_association, quasi_experimental, or simulation. A sentence that mixes these tiers is treated as a defect.
What the registered-data run supports
| Result | Evidence tier | Interpretation |
|---|---|---|
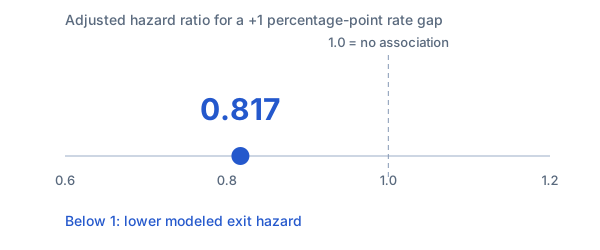
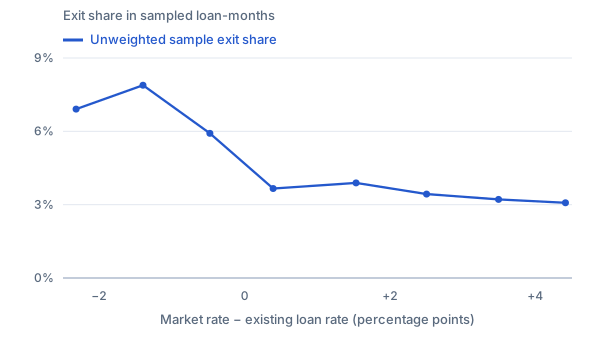
| Complementary log-log coefficient: -0.2018; hazard ratio: 0.817 per percentage point | Hazard association | Greater lock-in is strongly associated with lower monthly prepayment hazard after observed controls. This is not a causal elasticity and not a mobility estimate. |
| Purchase-originations estimates are negative at state and MSA levels | Descriptive | Pre-trends fail at both geographic levels, so greater precision does not earn causal interpretation. |
| Single-family permit event study | Quasi-experimental candidate | Pre-trends pass, but the estimate is statistically indistinguishable from zero. |
| Policy scenarios | Simulation | Useful for comparing modeled orderings, not for forecasting magnitudes. |
The honest headline is the ordering of evidence: the loan-level association is strong, while the market-level designs do not establish a causal effect on purchase activity, prices, or permits.
Reproduction and citation
Run make setup followed by make reproduce-sample for the public synthetic vertical slice. A registered-data run requires the user to obtain licensed Freddie Mac archives independently and place them in the documented local path; the project never bypasses registration or redistributes the files.
- Source, tests, and documentation
- Versioned publishable research package
- Open the interactive explorer
- Machine-readable metadata
Cite the Observatory release, Dataset revision, project repository, and every original data provider used in a run.
Evidence boundary
- Prepayment is not a home sale, refinance, or household move; the source does not separate those events.
- The Freddie Mac population excludes major mortgage segments and all-cash transactions.
- Predetermined exposure is not exogenous, and time effects absorb the common national rate shock.
- The demand-versus-supply decomposition is framed but not identified without listings, transactions, or household mobility data.
- Published scenario outputs rely on calibrated assumptions and are not forecasts.